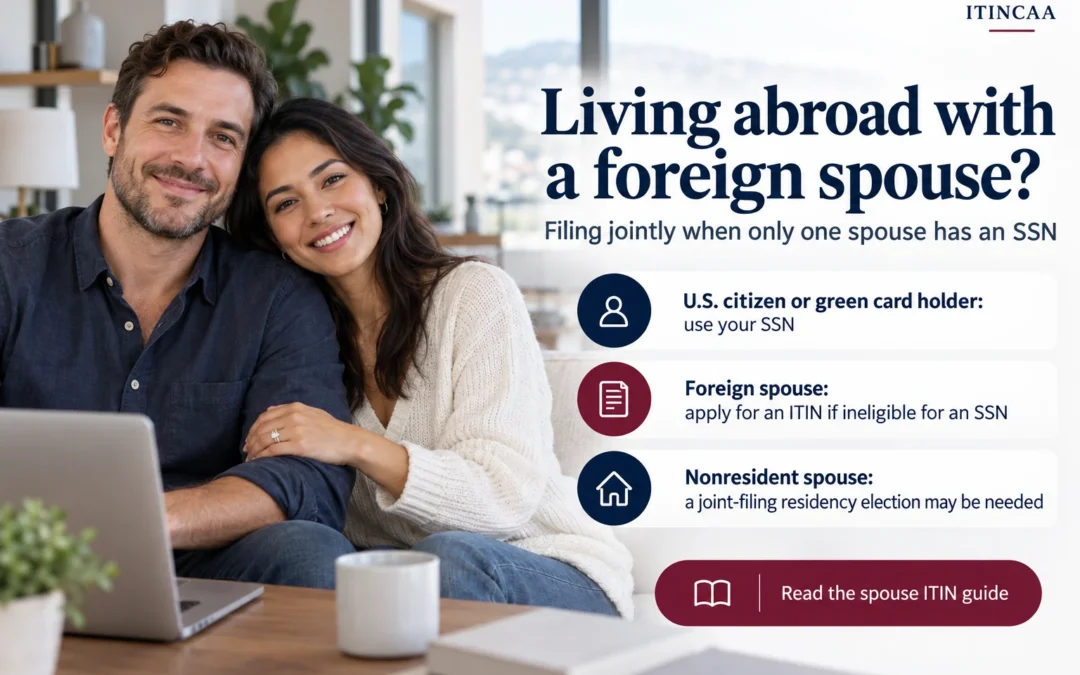
Living abroad with a foreign spouse who has no SSN?
If you are a U.S. citizen or green card holder, you use your SSN. Your foreign husband or wife may need an ITIN to join you on a U.S. tax return.
This guide is for a couple living outside the United States: one spouse is a U.S. citizen or a green card holder who remains a U.S. tax resident; the other is a foreign spouse without an SSN and ineligible to obtain one. They want to file a married filing jointly Form 1040.
In this situation, only the foreign spouse applies for an ITIN using Form W-7. The U.S. citizen or green card holder uses their SSN. If the foreign spouse is a nonresident for U.S. tax purposes, the couple generally also needs a valid election to treat that spouse as a resident for federal income-tax purposes. An ITIN application does not make that election. IRS nonresident spouse guidance.
Check SSN eligibility and the filing position before starting the application.
One spouse has an SSN, and the other needs an ITIN
Imagine a married couple living abroad. One spouse is a U.S. citizen with an SSN. The other is a foreign national, is not a U.S. tax resident, has no SSN, and is not eligible for one. They decide, after checking their filing position, to submit a joint U.S. return.
The foreign spouse is the Form W-7 applicant. Their U.S. citizen spouse does not apply for another tax number. The same application route can apply when the spouse with the SSN is a green card holder who remains a U.S. tax resident.
This is an illustrative example. Either the husband or the wife can be the ITIN applicant. The country where they live does not, by itself, establish ITIN eligibility; their U.S. tax position and reason for applying do.
Who needs the ITIN
An ITIN is for someone who needs a U.S. taxpayer identification number but is ineligible for an SSN. Having no SSN is not enough if the person can obtain one. U.S. citizens and lawful permanent residents are eligible for SSNs and should use that route. For this joint return, the eligible foreign spouse applies for the ITIN. Check any previously assigned SSN or ITIN before making a new application. IRS Form W-7 instructions.
Being married to a U.S. citizen or green card holder does not automatically require the foreign spouse to get an ITIN. This article concerns a spouse joining a joint U.S. return. If the couple does not file jointly and the foreign spouse has no other qualifying U.S. tax reason, an ITIN may not be needed. Foreign nationality alone also does not establish nonresident tax status; check the spouse’s actual residency position. IRS Form W-7 instructions.
Understand the joint return election
When one spouse is a U.S. citizen or resident, and the other is a nonresident at year-end, they can generally elect under section 6013(g) to treat the nonresident spouse as resident for federal income-tax purposes.
They must file jointly for the first election year and report both spouses’ worldwide income for that entire year. The election continues into later years unless suspended or ended. Filing separately later does not, by itself, cancel it. Ending it can prevent either spouse from making it again, even after remarriage. IRS election guidance.
For this couple, the practical point is straightforward: choosing resident treatment means including the foreign spouse’s income earned outside the United States, even though both spouses live abroad. If that spouse has no income, establish that fact when preparing the return. Obtaining the ITIN alone does not create this worldwide-income treatment; the residency election does. IRS nonresident spouse guidance.
Review worldwide income and the ongoing residency election before choosing to file jointly.
Check the joint filing consequences
A joint return may offer a better result, but the filing status alone does not establish a saving. Joint filers are generally each responsible for the full tax, interest and penalties on the return, subject to available relief. Without a residency election, married filing separately is commonly the U.S. citizen’s option; head of household requires separate qualifying conditions. A nonresident spouse alone is not a qualifying person for that status. IRS Publication 501.
Foreign tax credits may reduce double taxation on eligible foreign income, subject to limitations. Tax already paid overseas does not automatically erase the U.S. liability. IRS foreign tax credit guidance.
The question is whether a joint return is appropriate for these two spouses. Confirm that first, then prepare the foreign spouse’s ITIN application and any required election alongside the return.
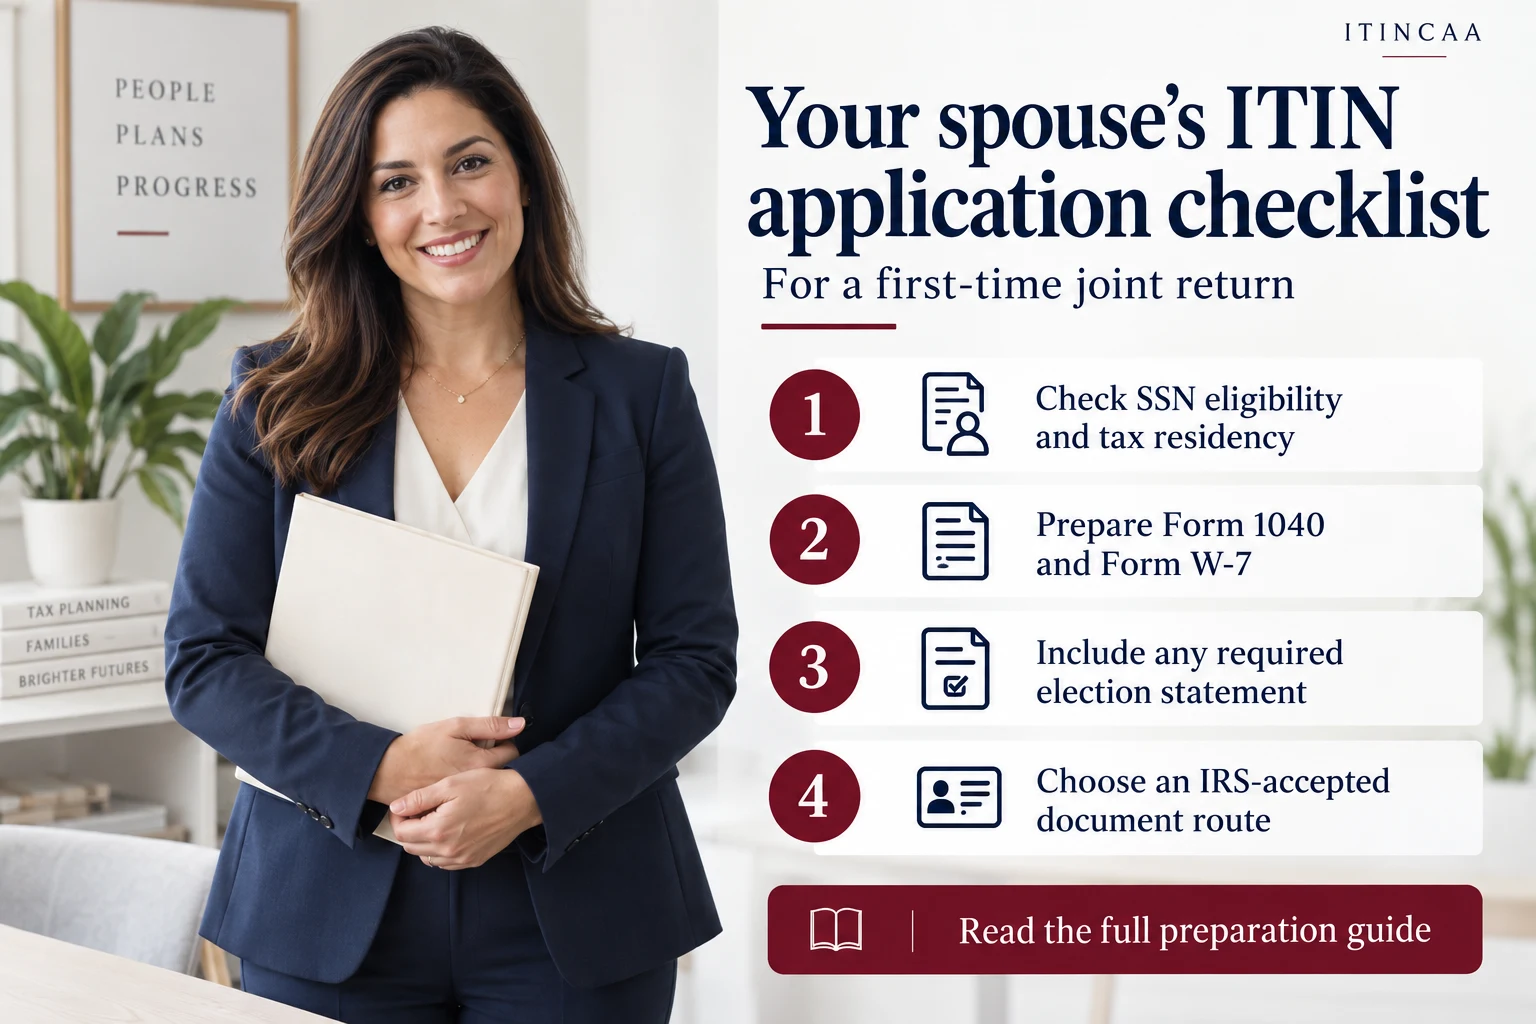
For a first-time joint return, prepare the tax return, W-7, and supporting documents together.
Prepare the return and application together
For this ordinary first-time spouse application, the working sequence is:
- Confirm the filing position. Check residency, SSN eligibility, any previous ITIN and any earlier residency election.
- Prepare the joint Form 1040. Include the required income and schedules. Both spouses generally sign.
- Prepare the election statement if required. Both spouses sign it. It identifies their year-end status, their choice of full-year resident treatment, and their names, addresses and tax identification details. Coordinate the new applicant’s pending ITIN with the W-7 package. IRS Publication 519.
- Complete Form W-7. Reason box e generally applies to an eligible spouse filing jointly with a U.S. citizen or resident. Include the U.S. spouse’s name and SSN as instructed. IRS W-7 instructions.
- Submit one complete package. Normally attach W-7 to the front of the paper return, with the supporting documents and required election statement. Leave the ITIN applicant’s SSN field on the return blank. The IRS assigns the ITIN and forwards the return for processing. Use the current ITIN submission instructions, rather than the ordinary Form 1040 mailing address. IRS application steps.
Retain a complete copy and evidence of submission. This gives your adviser a clear record if the IRS later asks for information.
Choose an accepted document route
For an adult spouse, a valid passport can generally establish identity and foreign status by itself. If mailing documents directly, the IRS generally requires originals or copies certified by the issuing agency. An ordinary photocopy, scan or routine notarised copy is generally insufficient. Special exceptions can apply, including certain military situations. IRS supporting document guidance.
An authorised Certifying Acceptance Agent can authenticate eligible documents under the IRS rules. Certain IRS offices also provide document authentication. A CAA is therefore one possible route, not a requirement for every applicant. Confirm the route before sending an original passport. IRS acceptance agent information.
Questions couples often ask
Can my spouse apply while living outside America?
Yes. Eligible applicants can apply from overseas. The IRS generally advises allowing seven weeks for an application-status notice, or nine to eleven weeks for overseas applications or peak-season submissions. These are estimates, not a guaranteed refund timetable. IRS application guidance.
What if my spouse has no income
Lack of income does not automatically prevent an eligible couple from electing to file jointly. Review the filing position and application requirements rather than assuming the spouse must earn income first. IRS Publication 519.
Do we need to wait for the ITIN before filing
For this first-time application, the return normally travels with Form W-7. Do not also send a duplicate return separately. An application does not automatically extend filing or payment deadlines. IRS Form W-7 instructions.
Does an ITIN provide immigration status or work permission
No. It is a federal tax identification number. It does not grant immigration status, work authorisation or Social Security benefits. IRS Form W-7 instructions.
Does filing jointly guarantee tax credits or a refund
No. Each credit has its own conditions, including identification-number requirements. Your income, tax payments and eligibility determine the result. Ask your preparer to check the rules for the particular tax year. IRS Publication 501.
Can your team certify my passport?
Our current service covers ITIN application preparation and coordination. We are not currently providing our own passport certification or signing Form W-7COA. Where appropriate, we coordinate with a separately authorised Certifying Acceptance Agent, subject to availability, or explain another IRS-accepted document route.
Get help with the application and the filing decision
Our team can help prepare your foreign spouse’s Form W-7 and coordinate it with your joint Form 1040 and any required residency election. Tell us whether the spouse with the SSN is a U.S. citizen or green card holder, where you both live, the tax year, and whether your foreign spouse has ever held an SSN or ITIN. Request secure document instructions before sending identity or financial records.
Discuss your spouse’s ITIN application and joint return at ITINCAA.
Accountants and other professional advisers can enquire about preparation and coordination support for clients living abroad with a foreign spouse. Please include the tax year, filing deadline and assistance required.
For related U.S. personal-tax work, see Tax and Accounting Hub’s U.S. tax services.
Disclaimer: This article provides general educational information as at 19 September 2026. It is not individual tax, legal or investment advice and does not create an adviser-client relationship. The correct treatment depends on your circumstances, the tax year, applicable law and treaties. Obtain advice before making an election or submitting an application. No tax saving, ITIN approval, processing time or refund is guaranteed.
Infographics use AI-generated illustrative people and do not depict actual clients. The tax points shown are explained in the article.